ADAS & Insurance Synergy
In 2026, the relationship between your car's sensors and your insurance premium is no longer speculative. Advanced Driver Assistance Systems—ranging from lane-keep assist to sophisticated 360-degree camera arrays—act as a "digital co-pilot" that insurers now scrutinize with the same intensity as your credit score or driving history. The primary goal for insurers like Progressive and Travelers is risk mitigation. When a car can "see" a pedestrian or anticipate a rear-end collision, the statistical likelihood of a high-value bodily injury claim drops significantly.
However, the "understanding" of this theme requires looking at the dual nature of these systems. On one hand, you have Frequency Reduction: fewer accidents mean fewer claims. On the other, you have Severity Increase: a minor "fender bender" that cost $800 in 2016 now costs $4,500 in 2026 because the bumper houses radar sensors that require precision calibration.
Real-World Data Points for 2026
- Claim Frequency: According to the Insurance Institute for Highway Safety (IIHS), vehicles equipped with comprehensive ADAS bundles saw a 39% drop in Property Damage Liability (PDL) claims this year.
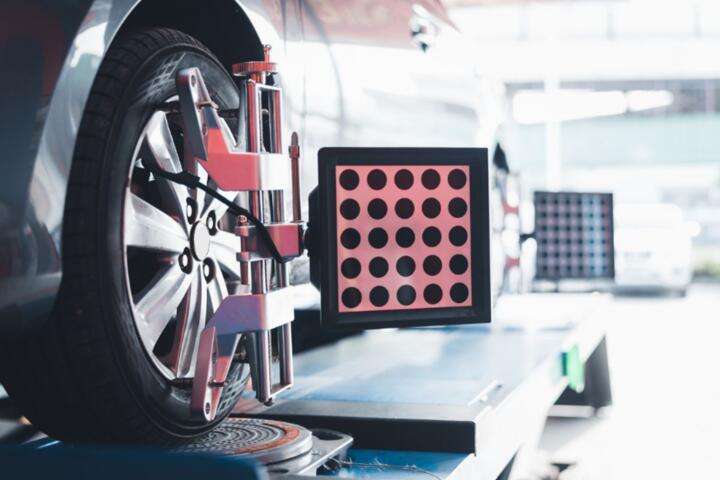
- Repair Inflation: The average cost for a windshield replacement on an ADAS-equipped vehicle has risen to over $1,200, as 90% of these replacements now require a static or dynamic camera recalibration.
Why Tech Raises Rates
The most common mistake drivers make is assuming that more safety tech automatically equals a lower bill. In reality, several "pain points" are causing premiums to spike for some of the safest cars on the road.
The first issue is Repair Complexity. A simple side-mirror clip on a 2026 model doesn't just involve glass and plastic; it often involves a blind-spot monitoring sensor and a side-view camera. If the technician at a local shop isn't certified for that specific OEM (Original Equipment Manufacturer) calibration, the system may fail, leading to secondary liability issues for the insurer.
Secondly, there is the Data Gap. Not all insurance companies have updated their actuarial models to recognize every proprietary safety suite. If you are driving a vehicle with a niche or very new ADAS platform, your insurer might default to a standard high-risk category because they lacks 5–10 years of historical "crash-loss" data for that specific hardware.
Real Situation: The "Total Loss" Trap
We are seeing an increase in "total loss" declarations for relatively minor accidents. Because the cost of replacing a front-end sensor array and performing the subsequent software "handshakes" exceeds 60-70% of the vehicle’s depreciated value, insurers are totaling cars that, ten years ago, would have been easily fixable. This trend pushes comprehensive coverage rates upward across the board.
Solutions for 2026
To combat rising costs, you must be proactive. Insurance in 2026 is no longer "set it and forget it."
Choose "Insurance-Friendly" Safety Suites
When purchasing a vehicle, look for brands that have partnered with insurers or have high IIHS TOP SAFETY PICK+ ratings. For example, the 2026 Rivian R1S has been noted for its high safety standards, which allows owners to negotiate better rates with specialized EV insurers like Stable.
Opt-In to Telematics and Connected Data
Most 2026 models are "connected cars." By opting into programs like Tesla Insurance or Ford Insure, you allow the insurance company to see exactly how your ADAS is being used. If the data shows that your Automatic Emergency Braking has intervened to prevent three potential accidents in six months, you aren't just a "safe driver" on paper—you are a proven lower risk.
Verify Calibration Coverage
Ensure your policy specifically includes "ADAS Calibration Coverage." Many standard policies have "windshield glass" riders, but in 2026, the glass is the cheap part. You need a policy that covers the $300–$600 calibration fee that follows the glass install. Using services like Safelite, which now standardizes ADAS recalibration in their quotes, ensures your insurer sees a professional, "closed-loop" repair.
Leverage Manufacturer-Specific Policies
In 2026, car manufacturers are increasingly becoming insurance providers. Because they own the data and the repair network, they can often offer rates 20% lower than traditional providers. They know the exact "fail-safe" metrics of their sensors, which reduces the "uncertainty premium" traditional insurers charge.
Regular Sensor Maintenance
Keep your sensors clean and the software updated. Some insurers are beginning to ask for "Vehicle Health Reports" during renewal. A car with a "Blind Spot Monitor Unavailable" warning on its dashboard is viewed as a high-risk vehicle, potentially voiding certain safety discounts.
ADAS Impact in Practice
Case 1: The Regional Delivery Fleet
Company: Mid-West Logistics.
Problem: Rising insurance premiums due to frequent low-speed backing accidents in urban areas.
Action: The company retrofitted 50 vans with 2026-spec Rear Cross-Traffic Alert and Rear AEB. They then switched to a "usage-based" policy that tracked ADAS engagement.
Result: Accidents dropped by 45%. After sharing the "near-miss" data with their underwriter, the fleet’s annual premium was reduced by 18% ($42,000 savings annually).
Case 2: The Individual Luxury SUV Owner
Driver: High-net-worth individual with a 2026 luxury SUV.
Problem: A $2,800 annual premium despite a perfect driving record.
Action: The owner provided "Safety Score" data from the vehicle's integrated app to a specialized broker at Marsh. They proved that 95% of highway miles were driven with Level 2+ autonomy (Adaptive Cruise + Lane Centering) engaged.
Result: The premium was recalculated based on "Assisted Driving" metrics, resulting in a $600 annual discount.
Feature Comparisons
| ADAS Feature | Expected Premium Discount | Primary Insurer Benefit | 2026 Status |
|---|---|---|---|
| Automatic Emergency Braking (AEB) | 10% – 15% | Reduces front-to-rear crashes | Industry Standard |
| Lane Departure Prevention | 5% – 8% | Prevents high-speed "drift" accidents | High Value |
| Blind Spot Detection | 3% – 5% | Reduces lane-change collisions | Common |
| Rear AEB / Parking Sensors | 2% – 4% | Reduces low-value property claims | Growing Impact |
| Driver Monitoring (DMS) | 5% – 10% | Mitigates distraction/drowsiness | Highly Rewarded |
Common Mistakes to Avoid
Overestimating "Autopilot" Capabilities
Many drivers treat Level 2 systems as "self-driving." In 2026, if an accident occurs and data logs show the driver’s hands were off the wheel for an extended period against the car’s warnings, insurers may deny the claim or significantly hike future rates. Always maintain engagement.
Skipping Professional Recalibration
Trying to save $400 by using a "glass-only" repair shop is a massive financial risk. If the ADAS camera is off by even a fraction of a degree, the AEB might trigger at the wrong time or not at all. In 2026, insurers check the "calibration handshake" logs during claims. No log means no coverage for the subsequent accident.
Ignoring Software Updates
Think of your car's software like a phone OS. Security patches and sensor logic updates are released frequently. Insurers like State Farm are starting to offer "Connected Tech" discounts, but these are often contingent on the vehicle running the latest safety firmware.
FAQ
Does every ADAS feature lower my insurance?
Not necessarily. While safety features like AEB generally lower premiums, others like "automated parking" may have a neutral effect. Insurers focus on features that prevent high-cost bodily injury and major property damage.
Why did my premium go up after I bought a car with more safety features?
This is likely due to the replacement cost. If your new car's headlights cost $2,000 each due to integrated sensors, the insurer must charge more for "Collision" and "Comprehensive" coverage to account for that potential payout.
Can I get a discount for retrofitting an older car with ADAS?
In 2026, most major insurers only provide significant discounts for "factory-integrated" systems. Aftermarket sensors often lack the "Vehicle-to-Everything" (V2X) communication that insurers trust for risk assessment.
How do insurers know if I’m actually using my safety features?
Through Telematics. If you have a "connected" policy, the car sends periodic data packets to the insurer. This doesn't usually include where you go, but rather "system health" and "intervention frequency" (how often the car had to help you brake or steer).
Will "Level 3" autonomous features make insurance cheaper?
Initially, no. Level 3 (where the car takes full control in specific conditions) shifts liability from the driver to the manufacturer. This creates a complex legal landscape that might actually lead to higher premiums until the legal precedents for "manufacturer liability" are fully settled.
Author’s Insight
From my perspective as an industry observer, the "Golden Age" of ADAS discounts is currently in a state of flux. While the tech is undoubtedly saving lives, the "repair economy" hasn't quite caught up, leading to the price friction we see today. My best advice: don't just look for a car with the most sensors; look for one with a "modular" sensor design where a small hit doesn't require a total front-end rebuild. Also, always shop for insurance every 12 months in 2026—the algorithms are changing so fast that loyalty to a single insurer can cost you hundreds in missed "tech-efficiency" discounts.
Summary
Navigating car insurance in 2026 requires a balanced understanding of how ADAS reduces risk but increases repair liability. To maximize your savings, prioritize vehicles with high safety ratings from the IIHS, opt into data-sharing telematics programs like Tesla Insurance or State Farm’s Drive Safe & Save, and always ensure that your policy covers the specific costs of sensor recalibration. By treating your car’s safety tech as a financial asset rather than just a convenience, you can successfully lower your premiums even in an era of rising repair costs.