EV Repair Hidden Costs
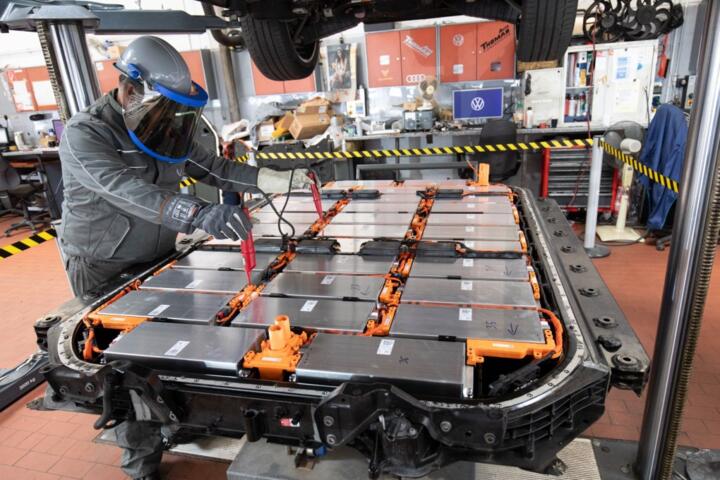
When a traditional internal combustion engine car gets a new bumper, the impact on value is negligible. However, when an electric vehicle (EV) requires a high-voltage battery pack removal, repair, or replacement, the vehicle’s "pedigree" is permanently altered. Even if a certified technician from a top-tier service center performs the work to factory specifications, the vehicle now carries a "repaired" status in databases like Carfax or AutoCheck.
In the secondary market, buyers are notoriously risk-averse regarding used batteries. A repair suggests the vehicle may have suffered kinetic trauma or a thermal event, leading to "stigma damages." Statistical data from automotive remarketing firms suggests that EVs with major battery interventions trade for 15% to 25% less than their "original factory seal" counterparts, regardless of the current state of health (SoH).
Consider a premium electric sedan valued at $70,000. After a $22,000 battery tray repair covered by insurance, the car might only fetch $55,000 on a trade-in. That $15,000 gap is your Diminished Value (DV), a legitimate loss that most insurance adjusters will never volunteer to pay.
EV Recovery Process Risks
The most common mistake owners make is assuming that "making the car whole" only refers to the mechanical function. Insurance companies often push for "remanufactured" or "refurbished" battery modules rather than new ones. While this restores the car to driving condition, it creates a massive red flag for future buyers who see a non-matching serial number or a history of high-voltage system intervention.
The consequences of ignoring this are purely financial and delayed. You won't feel the sting until you try to sell or trade the vehicle. Dealerships use software like vAuto to scan history reports instantly; once a battery repair is flagged, the automated valuation algorithms often apply a "structural/mechanical history" haircut that can't be negotiated away.
Real-world situations often involve insurers refusing to acknowledge DV on EVs because the battery is a "wear item." This is a fundamental misunderstanding of the technology. A battery pack in a modern EV is a structural component of the chassis. To repair it, the car is often dismantled in a way that affects long-term rigidity and resale perception.
The Impact of Carfax "Structural Damage" Flags
When a battery pack is replaced due to an accident, many collision centers report this as structural repair. This specific wording is a kiss of death for resale value. Buyers equate structural damage with a compromised safety cage, even if the work was limited to the battery housing.
The Problem with Non-OEM Battery Modules
Third-party repairers or insurance-mandated "quality recycled parts" can void portions of the manufacturer's drivetrain warranty. If a buyer learns that a vehicle has a "Frankenstein" pack—comprised of cells from different production lots—the value doesn't just diminish; it collapses.
Why "State of Health" Reports Aren't Enough
Owners often think a high SoH (State of Health) percentage (e.g., 98%) protects their value. It doesn't. A buyer doesn't just care about the capacity; they care about the history. A repaired pack is viewed as a higher fire risk and a lower reliability risk than an untouched factory pack.
The Insurance Adjuster’s "17c" Formula Trap
Many insurers use a dated formula (the 17c formula) to calculate diminished value. This formula caps the loss at 10% of the book value and applies heavy multipliers. For EVs, this formula is mathematically obsolete because it fails to account for the exponential price drops associated with EV battery stigma.
Difficulty in Private Party Resale
Try listing an EV on platforms like "Cars & Bids" or "Bring a Trailer" with a noted battery repair. The comment sections will be filled with skeptics. This lack of liquidity in the private market forces owners back to dealerships, who will lowball the trade-in precisely because they know the car is "tainted."
Full Equity Recovery
To successfully claim diminished value, you must move beyond the repair bill. You need a comprehensive Diminished Value Appraisal. Services like Collision Claims or DVCheck provide expert reports that utilize local market data rather than generic formulas. They compare your repaired EV against "clean" versions of the same model currently sitting on lots in your specific zip code.
In practice, this looks like presenting the insurance company with a 20-page document detailing "Inherent Diminished Value." This document proves that even though the car is fixed, its market value has dropped. For a high-end EV like a Porsche Taycan or a Tesla Model S, this claim can easily range from $8,000 to $18,000.
You should also demand a "Post-Repair Inspection" (PRI). A certified EV specialist should verify that the battery cooling loops were bled correctly and that the thermal management system is functioning at 100%. If the PRI finds even minor flaws in the repair, it further strengthens your claim that the vehicle's value is compromised.
Financial Recovery Cases
Case Study 1: The Premium SUV Collision
A owner of a 2023 Rivian R1S was involved in a rear-end collision that pushed the rear motor into the battery housing. The repair cost was $34,000. While the insurance paid for the repair, the owner noticed his trade-in offers dropped from $82,000 (pre-accident) to $61,000 (post-repair). By hiring an independent appraiser, the owner successfully argued for a $19,000 Diminished Value settlement from the at-fault party’s insurance.
Case Study 2: The Fleet Management Recovery
An enterprise car rental company had five Tesla Model 3s damaged in a hail storm, which dented the battery's protective shielding. The shields were replaced, but the "accident" appeared on the history reports. The fleet manager used a specialized appraisal service to prove a $4,500 loss per vehicle. The total recovery of $22,500 helped offset the increased depreciation at the time of fleet de-fleeting.
Post-Repair Checklist
| Feature | Factory Original Status | Post-Battery Repair Status | Impact on Value |
|---|---|---|---|
| Warranty | Full Manufacturer Coverage | Possible Partial Voiding | High |
| Market Appeal | Universal | Limited to Risk-Takers | Very High |
| Trade-In Ease | High (Instant Offers) | Low (Manual Appraisal Required) | Medium |
| History Report | Clean | "Electrical System Repair" Flag | High |
| Resale Delta | 0% | 15% - 30% Loss | Severe |
Step-by-Step Recovery Checklist
- Obtain the Final Repair Invoice: Ensure every part number is listed.
- Request a Battery Health Certificate: Get a digital readout of cell balance and SoH.
- Order an Independent Appraisal: Do not rely on the insurance company’s appraiser.
- Submit a Demand Letter: Formally request the specific dollar amount of the diminished value.
- Consult a "Diminished Value" Attorney: If the claim exceeds $10,000, legal counsel often pays for itself.
Common Claim Pitfalls
The biggest trap is signing a "Release of All Claims" before settling the diminished value portion. Once you sign that document to get your car back from the shop, you often waive your right to pursue the lost equity. Always keep the physical repair claim and the diminished value claim separate.
Another error is waiting too long. Statutes of limitations for property damage vary by state (e.g., 2 years in some, up to 6 in others). However, the longer you wait, the more "market volatility" the insurance company will blame for the price drop, rather than the repair itself. Documentation of the car's value immediately before and immediately after the repair is vital.
FAQ
Can I claim diminished value if the accident was my fault?
In most U.S. states, you cannot file a diminished value claim against your own insurance policy (first-party claim) unless you are in Georgia. Usually, DV claims are filed against the "at-fault" driver's insurance.
Does a battery replacement actually increase the car's value?
Insurance adjusters often argue "betterment"—that a new battery makes the car better than before. However, the market disagrees. The "stigma" of major work almost always outweighs the "benefit" of a newer battery in the eyes of a buyer.
How much does a professional DV report cost?
Typically, a high-quality, USPAP-compliant appraisal costs between $300 and $600. For high-value EVs, this is a small investment for a potential five-figure return.
Is diminished value available on leased EVs?
Generally, no. Since you don't own the asset, the loss in value is technically the leasing company's problem (e.g., Tesla Lending or Chase). You are only responsible for returning a repaired car.
Does a software-only battery fix trigger diminished value?
Usually not. If the "repair" was a firmware update to unlock capacity or fix a bug, it rarely appears on a vehicle history report as a significant repair event, thus preserving the value.
Author’s Insight
In my years of analyzing automotive markets, I’ve seen the "EV Stigma" become far more aggressive than the "Engine Rebuild Stigma" of the past. If you are driving an EV with a repaired battery pack, you are essentially holding a devalued currency. My advice: don't settle for a functioning car; demand a whole asset. The moment your repair is finished, get your independent appraisal immediately—before the market shifts and muddies your data.
Summary
Recovering diminished value after a battery pack repair is not just a suggestion; it is a financial necessity in the modern EV market. The delta between a "clean" vehicle and a "repaired" one is too large to ignore. By documenting the repair, securing an expert independent appraisal, and avoiding the traps set by insurance adjusters, you can reclaim the thousands of dollars in equity that are rightfully yours. Act quickly, stay organized, and treat your car's history report as a financial ledger that needs balancing.